Market Sentiment Tracker: Will the Global Economy End the Year on a Positive Note?
By
Osama
on October 28, 2025
in
Market Sentiment
The latest batch of global data looks encouraging but not in an “all clear” kind of way. Most of the major indicators from the U.S., Europe, and China pointed in the same positive direction last week, suggesting global activity is picking up. Still, one week of better numbers doesn’t erase the underlying risks: high borrowing costs, uneven demand, and geopolitical noise are all still in play.
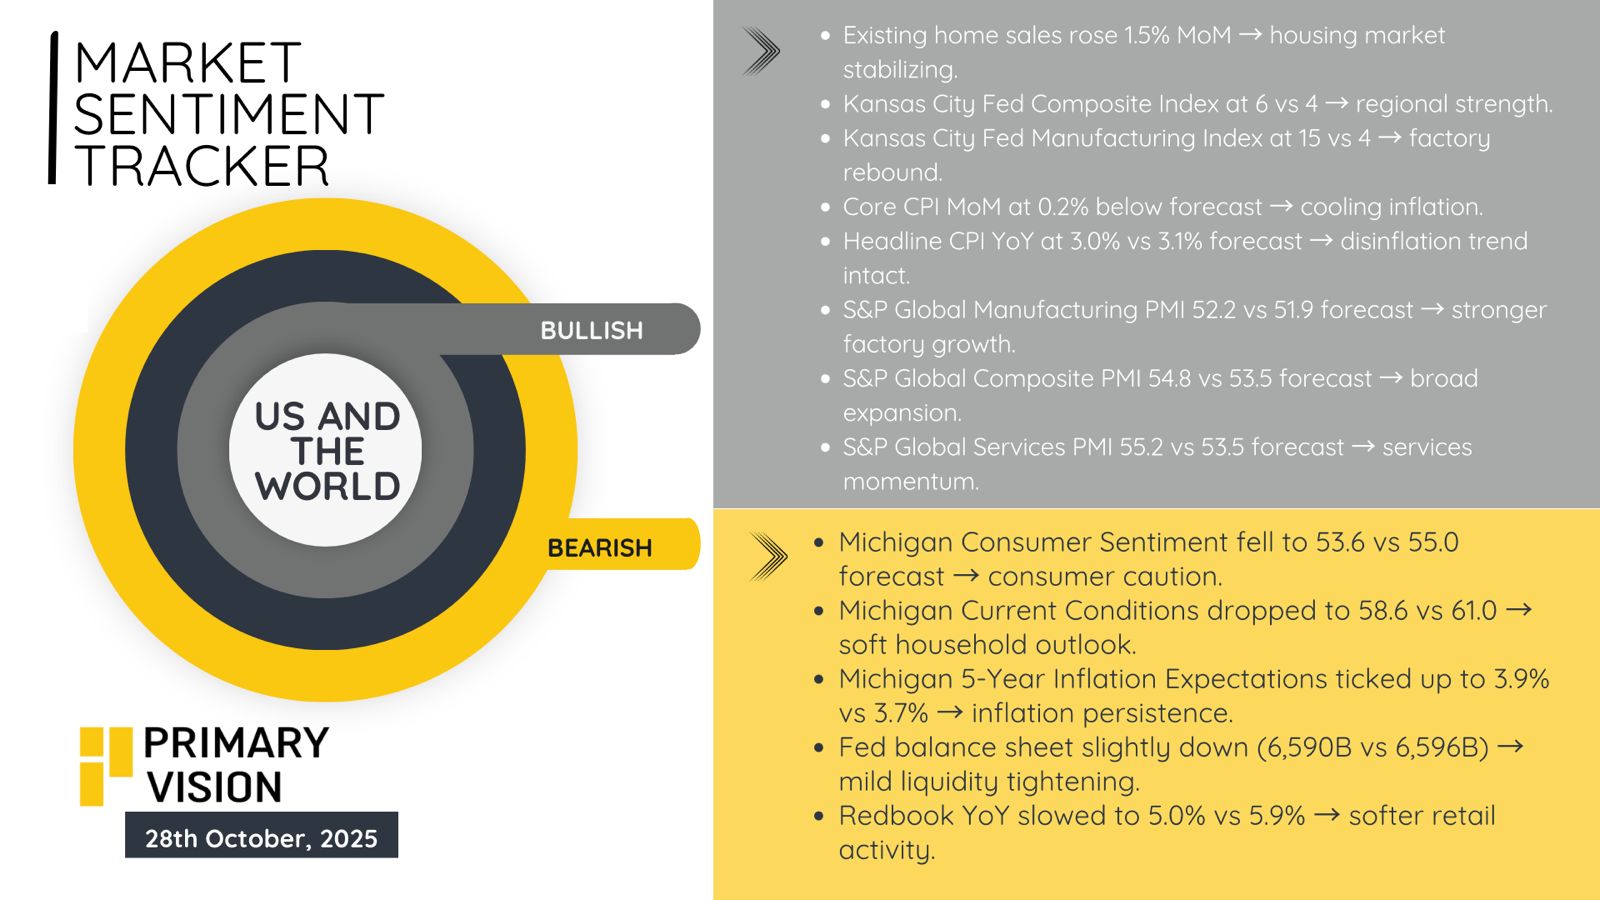
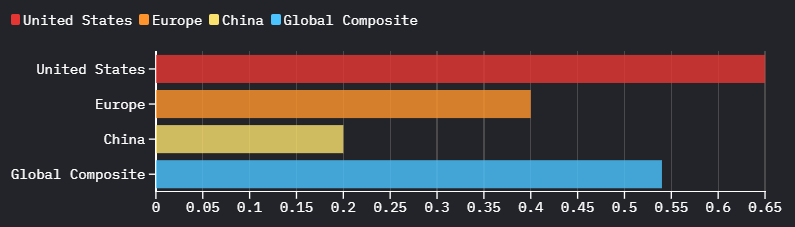
In the United States, the high-reliability indicators aligned. Inflation cooled further, with headline CPI at 3.0 percent year-on-year versus 3.1 expected and core CPI rising 0.2 percent month-on-month. The moderation in prices coincided with firm output readings. Manufacturing printed at 52.2, services at 55.2, and the composite at 54.8. The dual movement of softer inflation and stronger activity carries the highest signal weight in the current environment because it defines whether the Federal Reserve can maintain a neutral stance. Energy data confirmed that the improvement in activity is real. Crude and gasoline inventories fell sharply, and refinery utilization rose by nearly three percentage points, indicating strong end-demand. Existing home sales increased by 1.5 percent despite restrictive mortgage costs, supporting the view that the housing adjustment phase is stabilizing. Regional data from the Kansas City Fed were consistent with this pattern. Sentiment data weakened slightly, but those indicators historically carry low predictive value. Overall, the U.S. section of the data set produced a net positive score of roughly 0.65 on a scale where 1.0 reflects broad expansion.
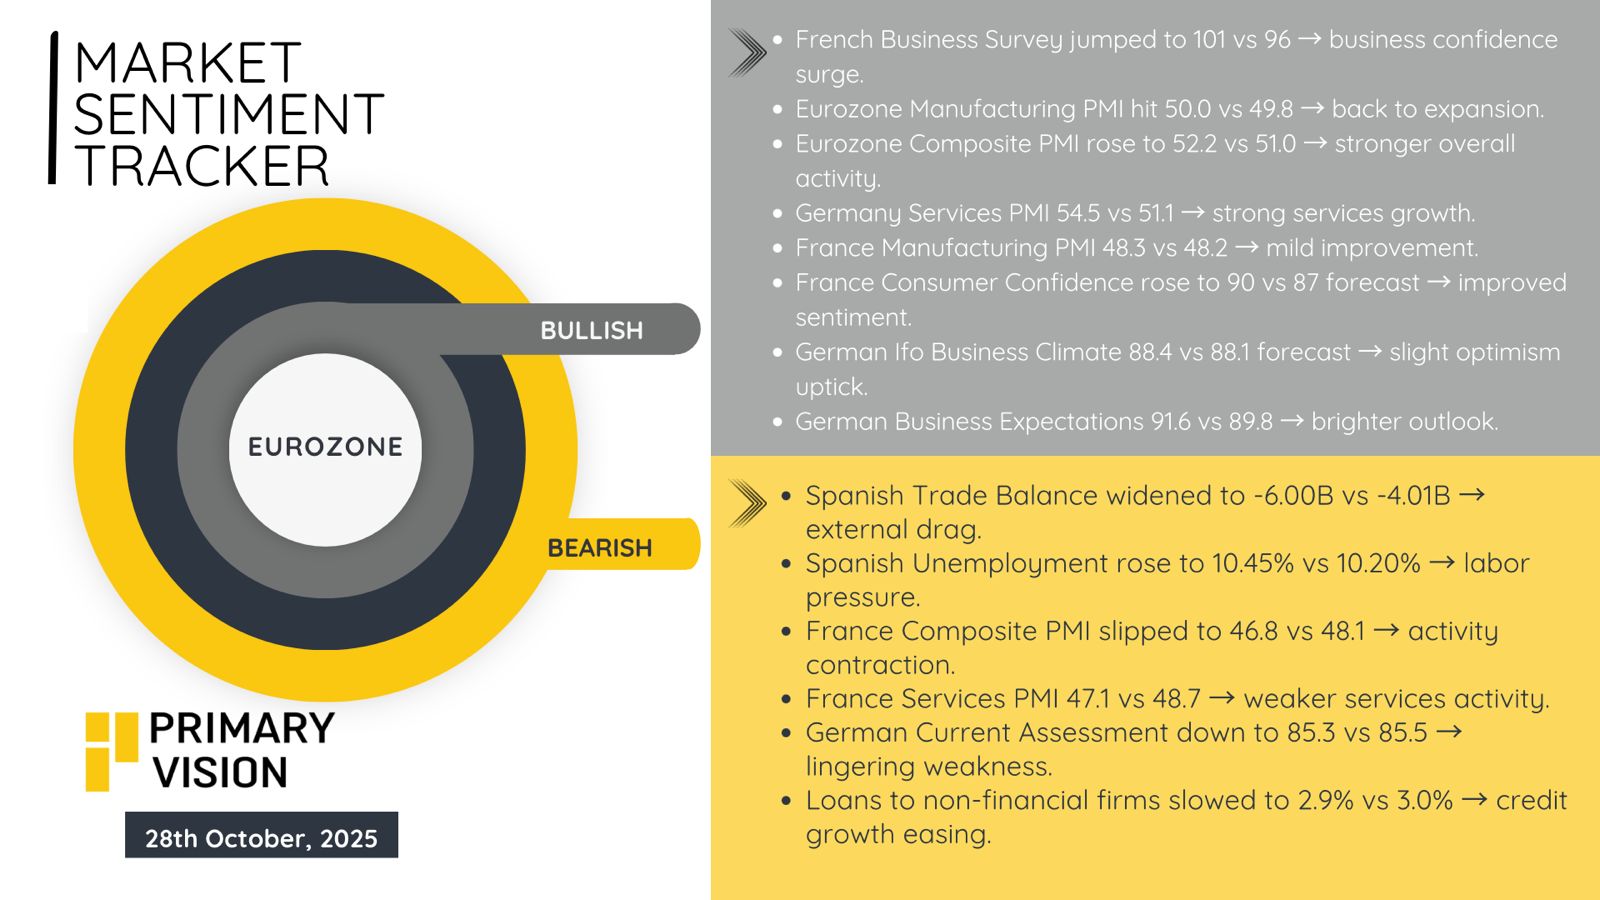
Europe delivered its first clean positive signal in months. The German composite PMI printed at 53.8, with services at 54.5 and manufacturing at 49.6. These readings, together with a Eurozone composite of 52.2, confirm that the core economies have moved back into expansion. The Ifo expectations index rose to 91.6 from 89.8, marking a second consecutive gain. France and Spain remained weak, but their combined weight in the Eurozone is not large enough to offset Germany’s improvement. Liquidity and credit aggregates were stable, showing no additional tightening. The European composite score stood near +0.40, implying early-stage recovery led by the core.
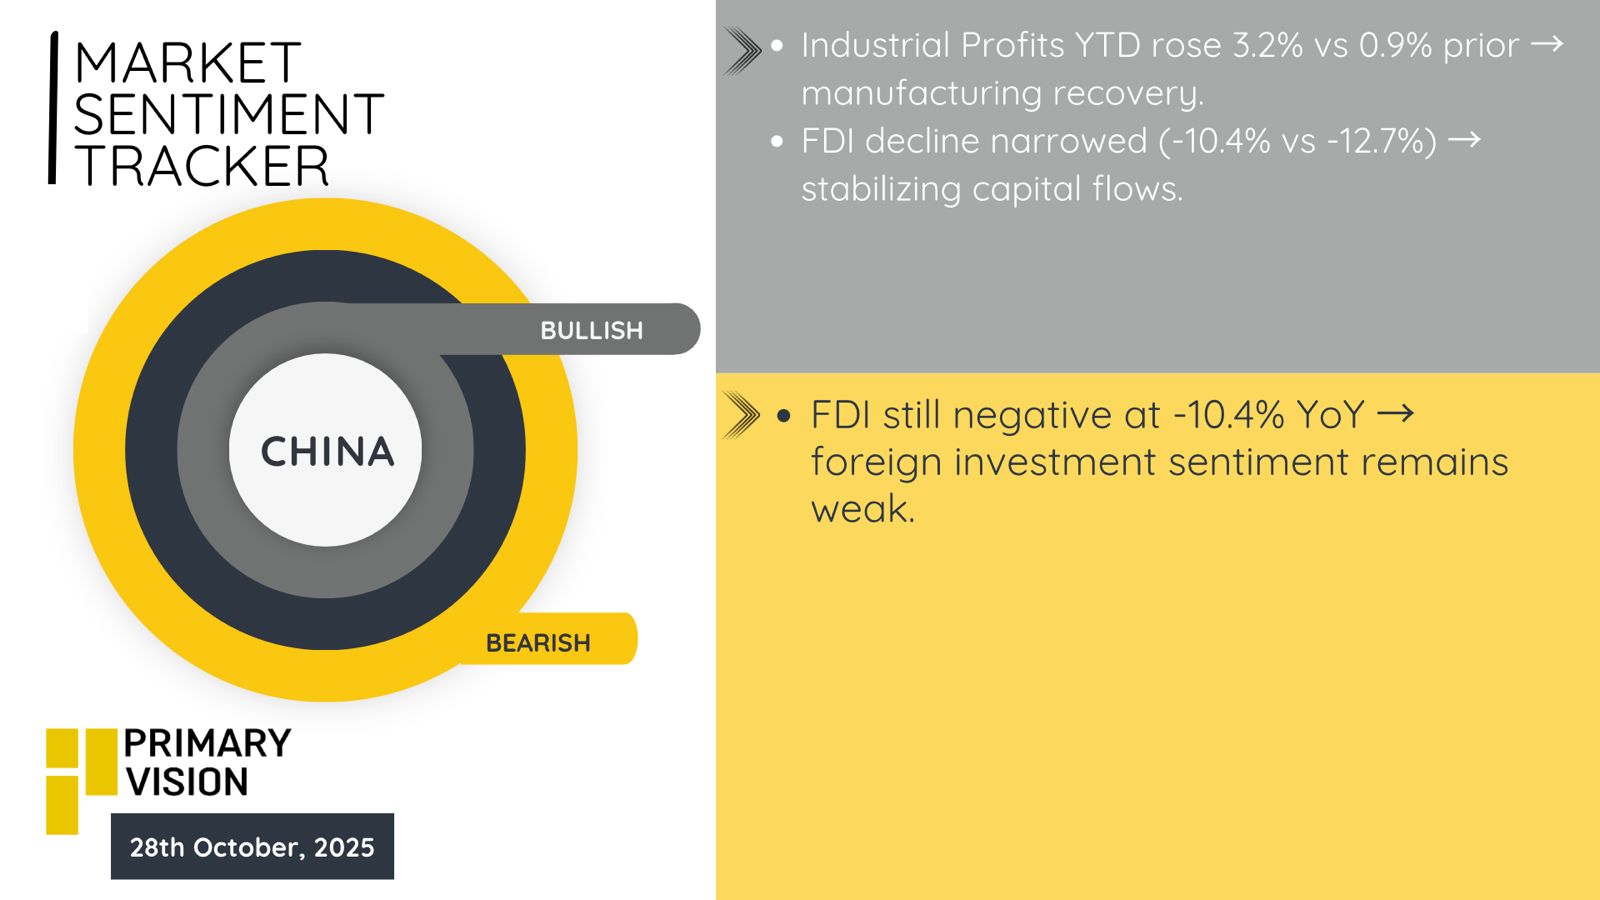
China’s contribution to the global picture was smaller but directionally consistent. Industrial profits rose 3.2 percent year-to-date compared with 0.9 percent in the previous release. The gain in profitability has stronger macro content than short-term production data because it tracks the underlying margin cycle. Foreign direct investment remained negative at –10.4 percent year-on-year, but the rate of decline slowed. On balance, China’s weekly signal was positive with a weight of +0.20, driven primarily by the improvement in domestic earnings.
Combining the regional scores and weighting them by GDP share gives a global composite of +0.54. The bulk of that strength comes from the United States and Germany. So it is not a broad based improvement rather there are certain nodes that have performed relatively better. Policy implications are straightforward: the Federal Reserve and the European Central Bank can remain on hold, and the People’s Bank of China can continue limited, targeted support.
The timing of this improvement is certainly interesting. We are headed into the year end and if it ends on a positive note for global economy then it is going to carry forward some of the optimism for the first quarter of 2026. Also, it means stock markets and other asset prices will remain elevated. However, in all of this we should not lose our sight at what lies underneath (something that I have been consistently highlighting through this Market Sentiment Tracker: debt fueled growth and tail risks). Now all eyes on U.S. - China trade deal. Expect another rally when that happens.
Upgrade to Pro Today and get…
• This article — plus dozens more each month, all within our full Research Module
• Frac Hits — our National-Level Frac Spread Count and Frac Job Count, updated weekly
• Frac Operator Monitor — detailed FSC & FJC by operator
• And so much more, designed to help you track, forecast, and outperform