


Articles
- BLOG / Articles / View
- Articles
Nabors Industries’ Perspective in Q2 2025: KEY Takeaways
By Avik on September 5, 2025 in Market Sentiment
Industry Outlook
We have already discussed Nabors Industries' (NBR) Q2 2025 financial performance in our recent article. Here is an outline of its strategies and outlook. According to the management, the global oil demand is strong, and the market appears stable with rising offshore and U.S. unconventional production. Tariff clarity and ongoing efficiency gains support this positive backdrop. Natural gas markets are resilient, boosted by growing LNG exports and rising rig counts. U.S. gas activity is recovering, and the company is positioned to benefit globally.
SANAD and International Market Update
Saudi Arabia is undergoing a major shift from oil to gas-focused drilling, leading to a significant drop in oil-directed land rigs. Since early 2024, 29 rigs have been idled, mostly from oil operations, while about half that number have started gas-related work. SANAD’s rig count has increased by four, and NBR has recently secured five more rig awards, with deployments planned through 2027. This positions SANAD to benefit from the Kingdom’s long-term gas development strategy and strengthens its outlook in a transforming market.
In the other regions in the Eastern Hemisphere, rig demand is rising with over 25 new opportunities identified, 40% of which are in markets where the company already operates. This growth could support higher industry utilization and pricing. In Mexico, rig redeployment interest is strong despite some uncertainty, and vendor payment challenges may ease with recent government intervention. In Argentina, activity is rebounding with new rig starts in the Vaca Muerta, expected to lift the rig count to 13 by early 2026, while Colombia also offers upside potential.
North America Outlook
Operator consolidation is still dampening drilling activity in U.S. oil basins, though the pace of decline is slowing. A recent survey of top Lower 48 operators suggests a slight 1% drop in aggregate rig count by year-end, with most expecting no change. Nabors expects its (own) rig count to remain stable through the rest of 2025.
In the US onshore, NBR expects its rig margin to decline sharply, by 19%, in Q3 compared to Q2. Internationally, however, its rig margin can improve by 2% in Q3.
Financial Performance
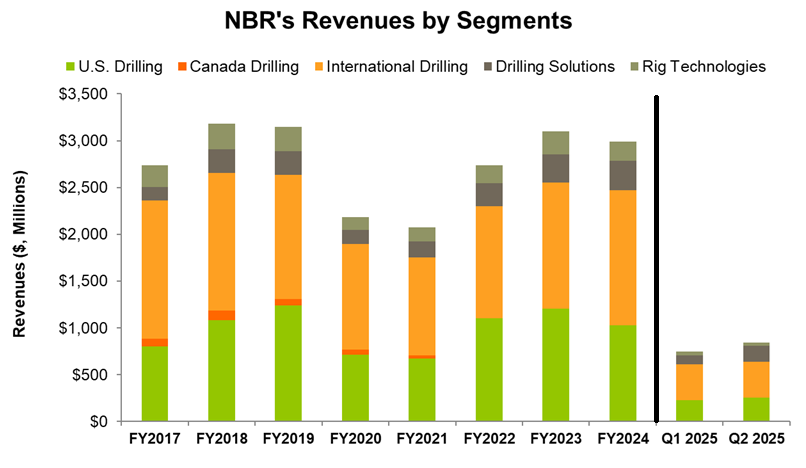
Quarter-over-quarter, revenues in the company's Drilling Solutions operating segment witnessed the sharpest rise (by 83%) in Q2, followed by the U.S. Drilling segment (11% up). Rig Technologies, on the other hand, witnessed a sequential revenue fall of 17%.
Nabors' priority is reducing debt. The company expects to generate free cash flow in 2025 and plans to use it for further debt reduction. A large customer financing effort is expected to resolve overdue payments, supporting Q3 free cash flow in line with Q2. Capex for 2025 is now guided at $700–710 million, down $70 million from earlier plans, with $300 million allocated to Saudi newbuild rigs.
Relative Valuation
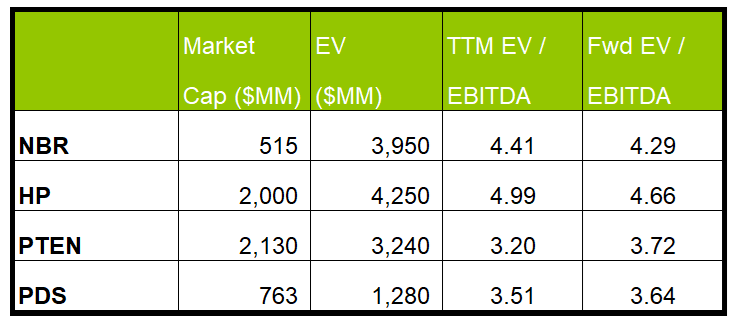
NBR is currently trading at an EV/EBITDA multiple of 4.4x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is lower. The current multiple is also lower than its five-year average EV/EBITDA multiple of 5.9x.
NBR's forward EV/EBITDA multiple versus the current EV/EBITDA multiple is expected to contract, contrasting the rise in multiple for its peers because the company's EBITDA is expected to increase compared to a fall in EBITDA for its peers in the next four quarters. This typically results in a much higher EV/EBITDA multiple compared to its peers. The stock's EV/EBITDA multiple is slightly higher than its peers' (NINE, PUMP, and ACDC) average of 3.9x. So, the stock is reasonably valued, with a positive bias, compared to its peers.
Final Commentary
Global oil demand remains strong with stable markets, rising offshore activity, and growing U.S. unconventional production, while LNG exports and rig additions support natural gas. In Saudi Arabia, Nabors is shifting toward gas-focused drilling through its SANAD JV, securing five new rig awards and expanding operations into 2027. Other international markets show rising rig demand, especially in Argentina and Colombia, while Mexico’s outlook may improve with recent government support.
In North America, drilling activity remains subdued due to operator consolidation, but Nabors expects its rig count to stay flat through year-end. U.S. onshore margins are set to decline in Q3, while international rig margins are expected to improve slightly. Nabors is focused on debt reduction, expects steady free cash flow, and has lowered its 2025 capex forecast to $700–710 million, with a major portion allocated to Saudi newbuilds. The stock is reasonably valued, with a positive bias, compared to its peers.
Tags:
Permission denied
Upgrade to Pro Today and get…
• This article — plus dozens more each month, all within our full Research Module
• Frac Hits — our National-Level Frac Spread Count and Frac Job Count, updated weekly
• Frac Operator Monitor — detailed FSC & FJC by operator
• And so much more, designed to help you track, forecast, and outperform