Natural Gas Market Outlook
We discussed our initial thoughts about Nine Energy Service's (NINE) Q2 2025 performance in our short article a few days ago. This article will dive deeper into the industry and its current outlook.
Nine remains optimistic on the medium- to long-term outlook for natural gas, supported by stable rig activity in Haynesville and the Northeast. Although overall activity declined in Q2, natural gas pricing helped drive more efficient operations and sentiment recovery in gas-heavy regions. The company’s Completion Tool and Wireline businesses benefited from this trend, even amid a tough macro environment. However, gains in gas basins may not fully offset Permian weakness, where lower activity and pricing continue to weigh on overall performance.
A sharp 10% drop in U.S. rig count in Q2, led by oil-weighted basins like the Permian, pressured Nine’s revenue and pricing across service lines in Q2. While natural gas prices declined, stable activity and improving sentiment in gas-levered basins like the Northeast provided partial support.
Strategic Focus
Nine is pursuing both growth and cost-efficiency strategies to boost margins and revenue. It is targeting market share gains, expanding internationally, and investing in R&D and a new Completion Tools facility. The company is reallocating assets and personnel to optimize utilization across regions. International revenue grew 20% in 1H 2025, highlighting early success. At the same time, it continues to reduce structural costs without compromising service quality.
Nine grew its Completion Tool revenue through stronger sales in the Haynesville and expanding international demand, particularly in the Middle East. With a 20% YoY increase in international tool revenue, the company sees continued upside in plug sales and multi-cycle barrier valves abroad.
The Wireline business saw an 11% revenue increase in Q2, driven by strong market share in the Northeast and growth in both pump-down and remedial services. However, declines in Cementing and Coil—limited to the Permian—dragged on overall performance due to regional exposure.
Q3 Forecast
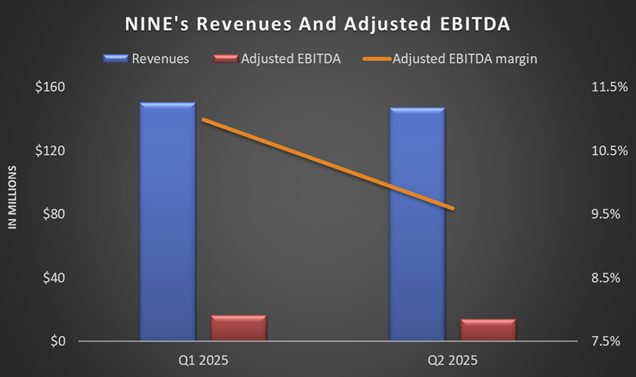
Nine expects Q3 revenue and adjusted EBITDA to decline due to full-quarter impacts from Q2’s pricing and activity cuts. Calendar gaps in oil-levered basins will add further pressure. However, the company aims to protect margins through diversification and operational agility. We have already discussed its Q2 results, balance sheet, and cash flows in the short article here.
Relative Valuation
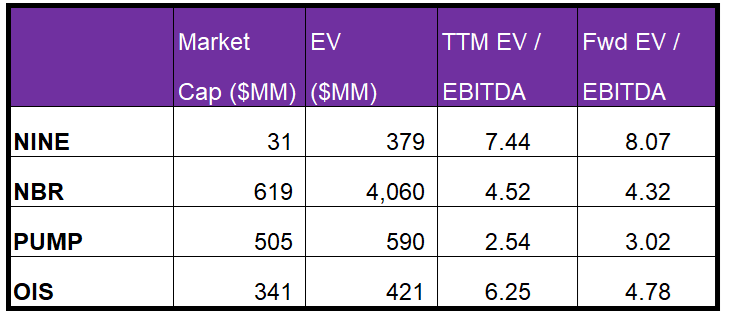
NINE is currently trading at an EV/EBITDA multiple of 7.4x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is higher.
NINE's forward EV/EBITDA multiple compared to the current EV/EBITDA is expected to expand compared to an unchanged multiple for its peers. This implies that its EBITDA is expected to decrease compared to an unchanged EBITDA for its peers in the next year. This typically results in a lower EV/EBITDA multiple than its peers. The stock's EV/EBITDA multiple is higher than peers' (NBR, PUMP, and OIS) average. So, the stock is relatively overvalued compared to its peers.
Final Commentary
Nine remains optimistic about natural gas, citing stable rig activity and improved sentiment in Haynesville and the Northeast. But these gains are unlikely to offset continued pricing and volume weakness in the Permian. Management is focused on both growth and defense—pursuing international expansion, reallocating assets, and cutting costs. Completion Tool sales rose in the Haynesville and the Middle East. Wireline also improved, especially in the Northeast, but declines in Cementing and Coil dragged on Q2 performance.
NINE’s Q3 revenue and EBITDA are expected to fall further, reflecting the full impact of pricing and activity cuts made in Q2. The stock is relatively overvalued compared to its peers.