Industry Outlook and Project Summary
NOV expects geopolitical uncertainty to keep creating near-term disruption, with some Middle East customers moderating drilling programs in Q4. Beyond the near term, energy-security needs, inventory replenishment, and a decade of restrained investment support demand for modern equipment and technologies that improve efficiency and project economics. Management expects Q4 revenue to be roughly flat year over year and adjusted EBITDA of $260 million to $300 million.
Q3 awards included global offshore-fleet data aggregation and remote monitoring through the Max Platform; mooring systems for floating production projects in the U.S., Eastern Mediterranean, and Angola. NOV also received a composite linepipe order in Oman, plus six well-service rig electrification conversions. Additional wins covered offshore wind installation vessels, North American rig upgrades, water-injection pumps, and drilling technologies in the U.S. and Australia.
Segment Performance in Q3
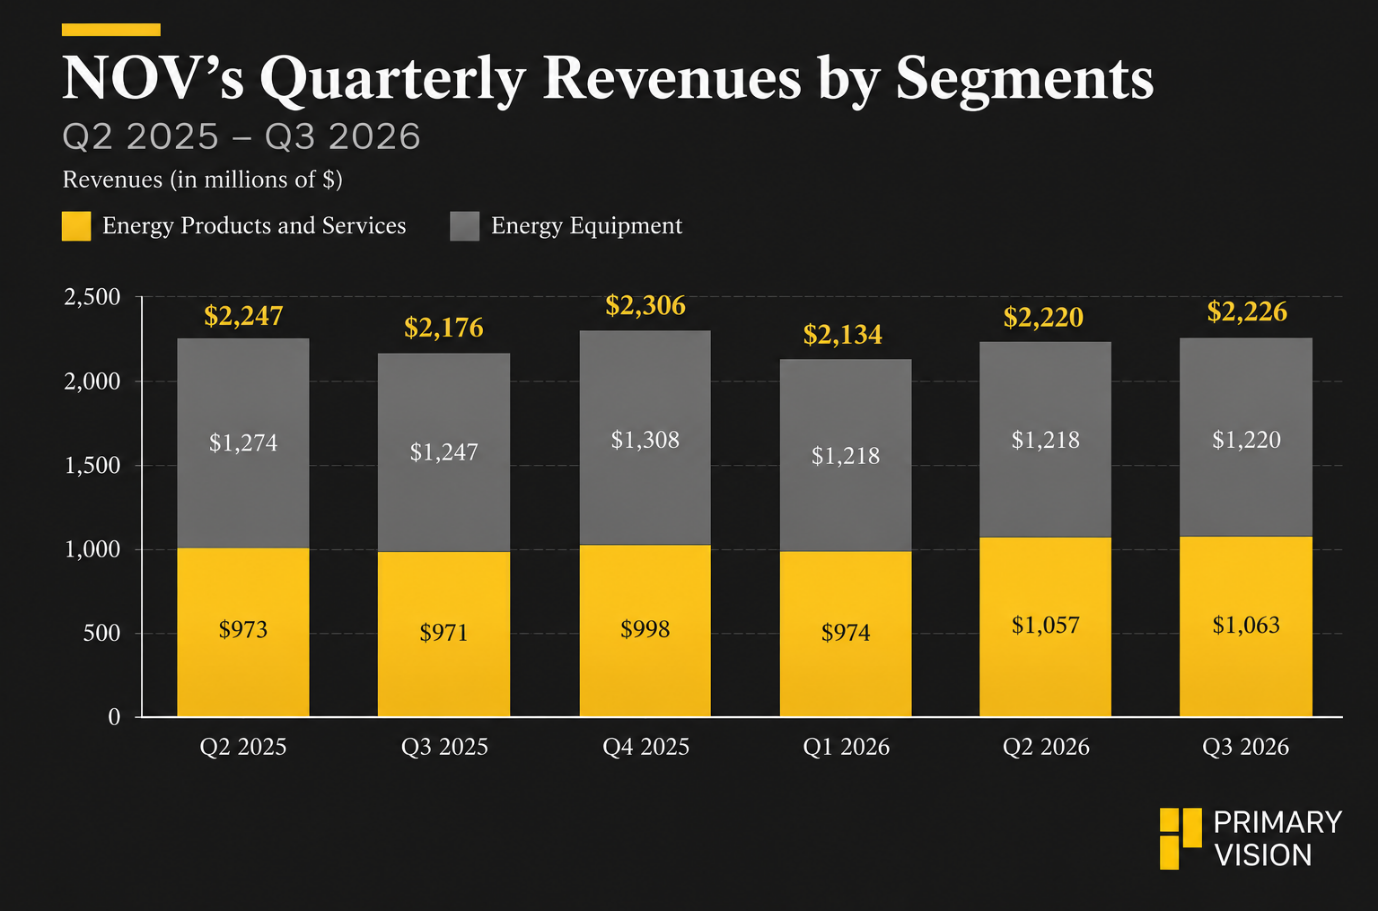
Energy Equipment revenue was essentially flat sequentially at $1.22 billion in Q3, while adjusted EBITDA declined 6%. Completion of certain offshore production projects weighed on revenue, partly offset by stronger demand elsewhere; margins benefited from favorable project mix and improved margins in backlog. The segment ended September with quarterly bookings of $577 million and produced a 91% book-to-bill ratio.
Energy Products & Services revenue rose 9% sequentially, and adjusted EBITDA increased 6%. Higher manufacturing throughput against a growing drill-pipe and composite-equipment backlog, along with cost and efficiency gains, supported the improvement. The key near-term question is whether NOV can continue converting its backlog into shipments and margin gains as Middle East activity moderates.
Cash Flows and Shareholder Returns
NOV generated a steep decline in operating cash flow in 9M 2026, but free cash flow was negative $202 million. Working capital consumed $251 million during Q3. Cash and total debt were broadly unchanged from year-end 2025—alongside $1.5 billion of available revolving credit. NOV returned $47 million to shareholders during Q3.
Thanks for reading the NOV Take Three, designed to give you three critical takeaways from NOV's earnings report. Soon, we will present a second update on NOV earnings highlighting its current strategy, news, and notes we extracted from our deeper dive.