Market Outlook
Nabors expects further sequential adjusted EBITDA growth in Q4, led by U.S. Drilling. The Lower 48 working fleet is expected to expand by ~7%, while daily adjusted gross margin should remain broadly stable. International Drilling’s rig count is expected to decline by 2%, but daily adjusted gross margin could improve by ~2%. These forecasts incorporate the suspension of five SANAD rigs, partly offset by newbuild deployments extending into early 2027. A multiyear contract in Venezuela, beginning in early 2027, adds another international growth avenue.
Management expects FY2026 adjusted EBITDA to reach the upper end of its guidance (approximately $930 million), with stronger cash generation supporting continued debt reduction. It also targets an annualized adjusted EBITDA run rate of ~$1 billion heading into 2027.
Key Performers in Q3
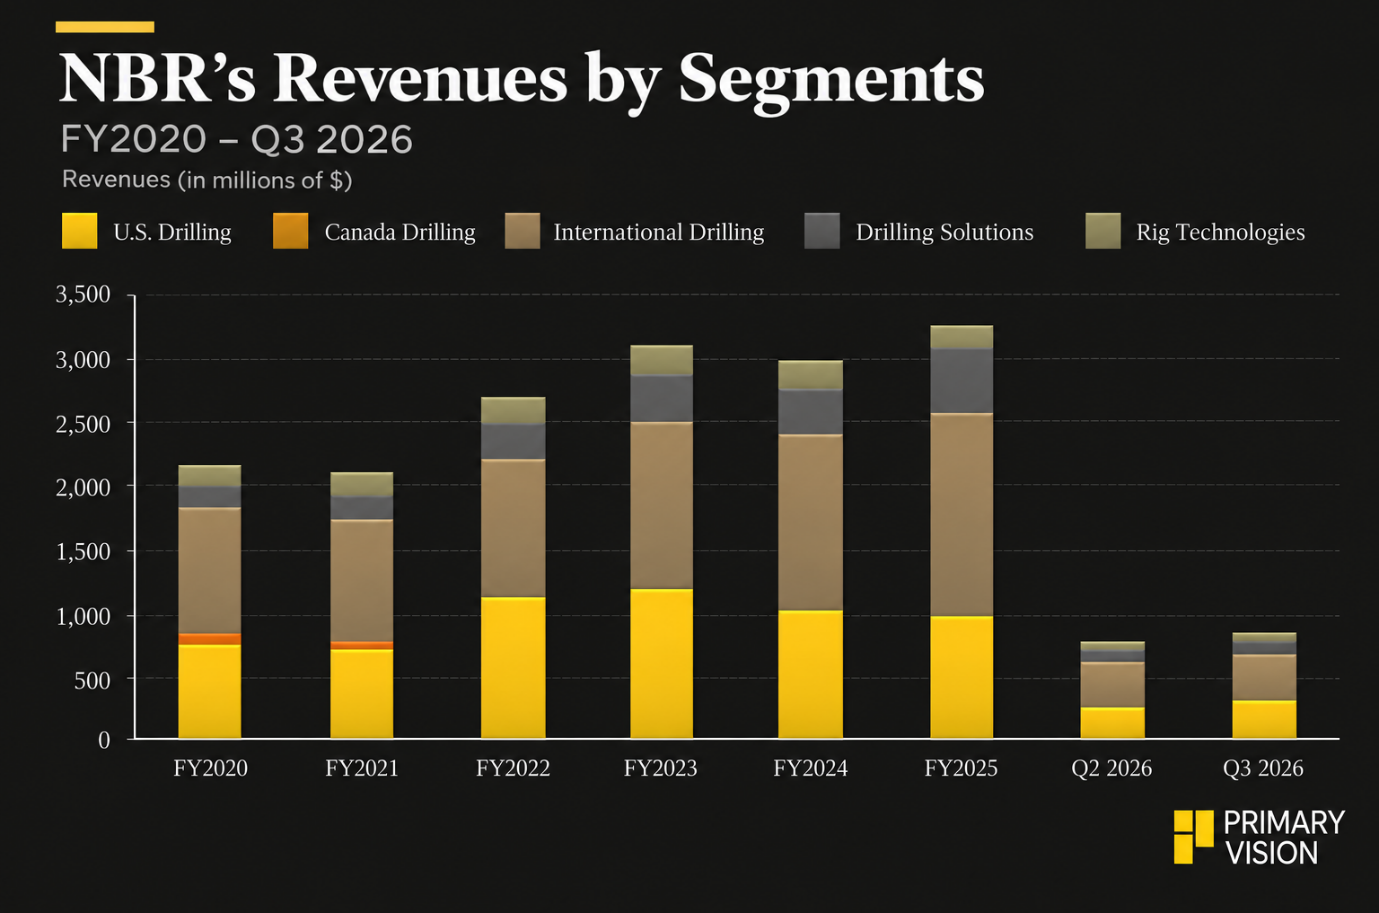
NBR’s Q3 adjusted EBITDA increased 11% sequentially in Q3 2026. International Drilling led with a record $19,060 daily adjusted gross margin, up 8.7%. U.S. Drilling EBITDA rose to $99 million as the average Lower 48 working fleet expanded 7% sequentially.
Drilling Solutions EBITDA increased by 10%, supported by greater adoption of Performance Software and Downhole Services; Rig Technologies improved marginally, with aftermarket revenue and equipment sales increasing.
Cash Flows & Debt
Free cash flow turned positive to $39 million in 9M 2026 from negative $56 million in 9M 2025, reflecting higher profitability, lower capital spending, and improved working capital. Q3 capex was $164 million, and management expects it to increase to $250-$260 million in Q4. Total debt declined 19% from year-end 2025 after Nabors redeemed $100 million of notes.
Thanks for reading the NBR Take Three, designed to give you three critical takeaways from NBR's earnings report. Soon, we will present a second update on NBR's earnings, highlighting its current strategy, news, and notes we extracted from our deeper dive.