Key Drivers And Outlook
Our short article discussed our initial thoughts about KLX Energy Services' (KLXE) Q2 2025 performance a few days ago. KLX expects Q3 2025 to be its strongest quarter of the year, continuing a seasonal pattern and benefiting from strong positioning with top U.S. onshore customers. The management projects sequential revenue growth in the low to mid-single digits and continued margin expansion, supported by customer awards, completions program restarts, and consistent operational execution.
KLXE remains optimistic about long-term U.S. natural gas fundamentals, with LNG export capacity growth over the next 12–24 months expected to drive incremental activity. Its strong presence in gas-focused basins positions KLX to capitalize on this growth, with Q2 dry gas revenue up 25% sequentially, though still 40% below Q1 2023 peaks.
KLX’s short-term outlook indicates a fully loaded quarter, minimizing the risk of unexpected white space. Recent wins from off-cycle RFQs are expected to contribute incremental work across multiple basins. The company also highlights the importance of operational discipline, balance sheet flexibility, and proactive risk management in navigating a volatile macro backdrop. These factors, combined with measured top-line growth, are expected to enhance profitability through the rest of 2025.
Outlook Explained
KLX does not expect significant Q4 budget exhaustion in the Haynesville. Marcellus and Utica may face some risk due to strong early-year activity and stable rig counts. Management has not seen signs of budget exhaustion yet but remains cautious.
Current Challenges
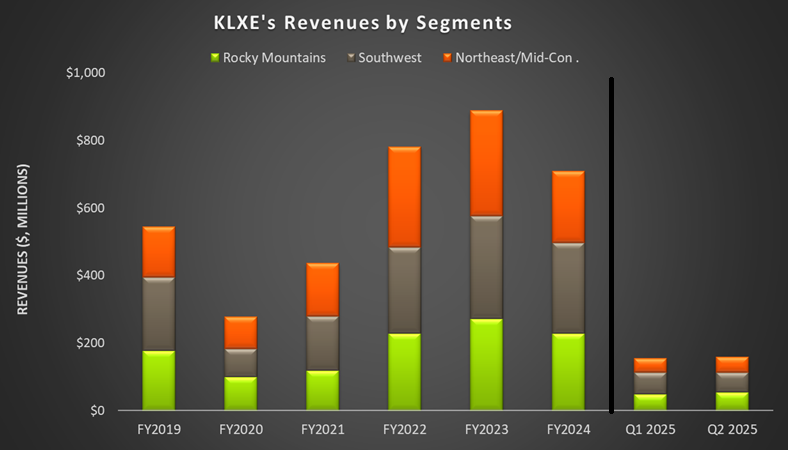
We discussed KLXE’s Q2 performance in detail in our short article. Here, we will discuss the challenges. KLX saw strong sequential improvement across its completion and production portfolio in Q2. The company managed staffing challenges in the Permian by sharing personnel across districts. Over half of revenue occurs post-frac, making labor utilization critical amid volatile schedules. Despite macro headwinds, KLX’s diversification and customer alignment supported relative outperformance.
Relative Valuation
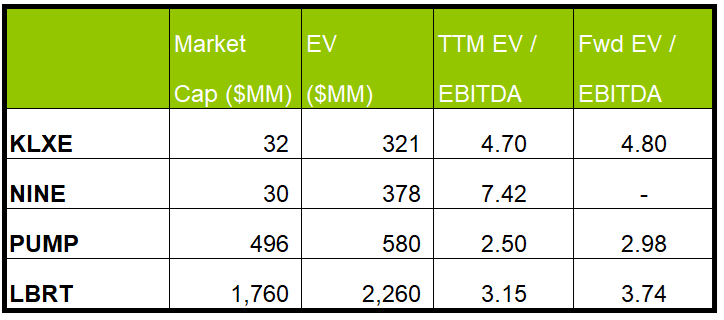
KLXE is currently trading at an EV/EBITDA multiple of 4.7x. Based on sell-side analysts' EBITDA estimates, the forward EV/EBITDA multiple is higher (4.8x).
KLXE's forward EV/EBITDA multiple expansion versus the current EV/EBITDA is less steep than its peers' because its EBITDA is expected to decrease less sharply than its peers in the next year. This typically results in a higher EV/EBITDA multiple than its peers. The stock's EV/EBITDA multiple is higher than its peers' (NINE, PUMP, and LBRT) average. So, the stock is reasonably valued, with a positive bias, compared to its peers.
Final Commentary
KLX expects Q3 2025 to be its strongest quarter, with sequential revenue growth in the low to mid-single digits and margin expansion supported by customer awards, program restarts, and strong execution. Long-term U.S. natural gas fundamentals remain positive, with LNG export growth over the next 12–24 months expected to boost activity, especially in gas-focused basins. Q4 budget exhaustion risk is low in Haynesville but could be higher in Marcellus and Utica due to strong early-year activity.
Operational discipline, balance sheet flexibility, and proactive risk management remain key to navigating a volatile macro environment. Despite Q2 staffing and scheduling challenges from customer completion holidays, KLX’s diversification and customer alignment drove relative outperformance. The stock is reasonably valued, with a positive bias, compared to its peers.